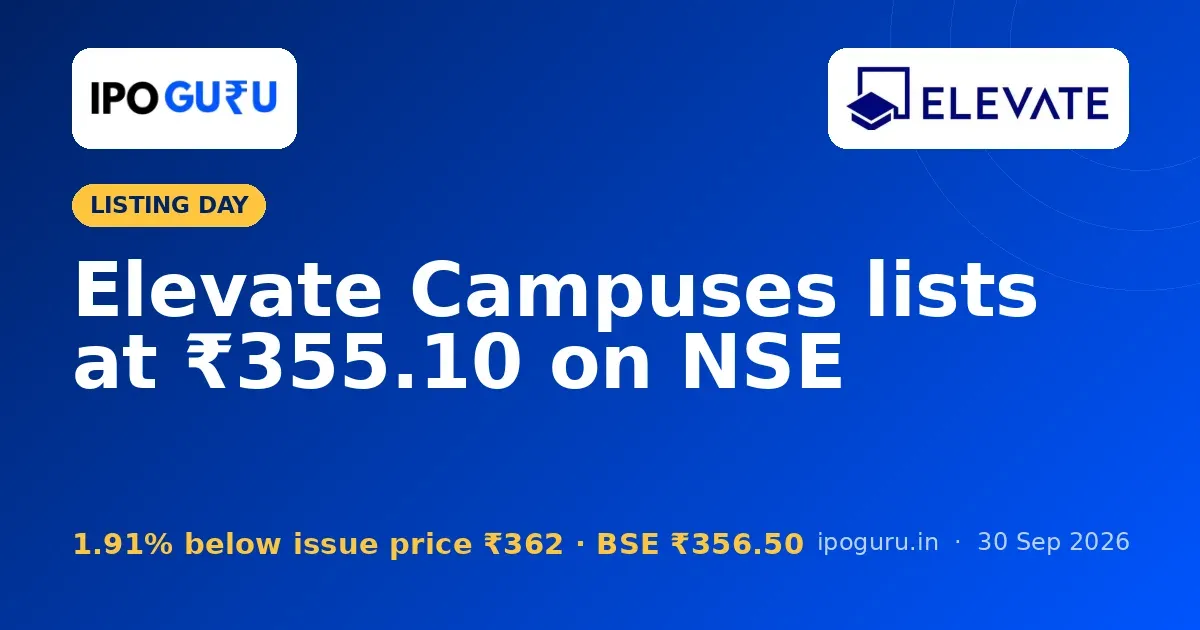
The Elevate Campuses IPO listing went the way its order book had warned. The shares opened at ₹355.10 on the NSE on 30 September 2026, 1.91 per cent below the ₹362 issue price. On the BSE they opened at ₹356.50, a discount of 1.52 per cent.
This was a ₹2,100 crore issue, all of it fresh capital. It closed on 25 September with bids for only 1.79 times the shares on offer.
The book was thin for a ₹2,100 crore issue
Most mainboard issues this month closed many times over. This one barely got past the line, and one category did not get there at all.
| Category | Subscribed |
|---|---|
| Qualified institutional buyers (QIB) | 2.52x |
| Non-institutional investors (NII), total | 0.84x |
| NII above ₹10 lakh (bNII) | 0.83x |
| NII ₹2 lakh to ₹10 lakh (sNII) | 0.88x |
| Retail | 1.01x |
| Total | 1.79x |
Read the NII line first. At 0.84 times, the portion for investors applying above ₹2 lakh was left unfilled. Retail at 1.01 times means the small investor portion was covered and nothing more, so almost every valid retail application would have received a lot.
QIB at 2.52 times carried the issue. When institutions are the only real bidders and the wealthy individual money stays away, there is nobody queued up to buy on listing day. That is what a flat to negative open looks like before it happens. The category split is on our Elevate Campuses subscription page.
The grey market read it almost right
Our tracker showed a grey market premium of ₹6.50 on 30 September, or 1.80 per cent. That pointed to a listing around ₹368.50. The NSE open was ₹355.10, so the unofficial quote was ₹13.40 a share out, and it had the direction wrong. It was still far closer than the usual miss. The quote had been ₹10 on 26 September and drifted down to ₹6 by 28 September, which is the grey market cooling off as the weak book became public. GMP is an unofficial dealer quote and no exchange stands behind it.
What one lot cost, and what it is worth now
The lot size was 41 shares, so the smallest application at the ₹362 upper band cost ₹14,842. At the ₹355.10 open that lot was worth ₹14,559.10, which is ₹282.90 less than the cheque. Our IPO page showed the stock at ₹352.40 soon after the open, which puts the lot at ₹14,448.40.
These are small sums on one lot. The point is the direction, not the size. An issue this large needs steady buying after listing, and the first prints did not show it.
What the money is being used for
All ₹2,100 crore is fresh capital, so every rupee goes to the company and none to selling shareholders. Here is where it is going.
| Use of proceeds | Amount |
|---|---|
| Buying the K-12 school entities and campuses | ₹1,100 crore |
| Repaying borrowings of the company and named subsidiaries | ₹750 crore |
| Unidentified acquisitions and general corporate purposes | Balance |
Elevate Campuses was set up in 2005 and owns, builds and runs student housing on the campuses of colleges and universities, under the Good Host Spaces and ScholarZ brands. As on 31 March 2026 its pre acquisition group had beds for 80,255 students across 15 Indian cities and one city in the United Arab Emirates.
Seven campuses with 20,368 beds are owned outright. Another 14 campuses with 55,487 beds are run for other owners. Its owned beds ran at 89.37 per cent occupancy in the 2025-26 academic year. It works with institutions including Manipal Academy of Higher Education and Manipal University Jaipur.
The number the book was probably reacting to
Total income rose from ₹362.61 crore in FY2024 to ₹603.39 crore in FY2026, and profit after tax went from ₹39.69 crore to ₹173.76 crore over the same two years. The EBITDA margin is 90.32 per cent, which is what owning property looks like on a profit and loss statement.
Then there is the balance sheet. Total borrowing was ₹4,120.53 crore as on 31 March 2026 against a net worth of ₹956.29 crore. That is a debt to equity ratio of 4.98, and the borrowing more than tripled in a single year from ₹1,206.60 crore. Return on capital employed was 6.42 per cent despite that 90 per cent margin, because so much capital is tied up in the buildings.
The issue was priced at 35.11 times post issue earnings on earnings per share of ₹10.31, valuing the company at ₹6,100.82 crore. At ₹355.10 that value is about ₹5,985 crore, on our arithmetic. The ₹750 crore of debt repayment takes borrowings down, but not by most of ₹4,120 crore.
What happens next
The dates are behind us. The issue ran from 23 to 25 September, allotment was finalised on 28 September, and refunds and demat credits went out on 29 September. KFin Technologies was the registrar. JM Financial, IIFL Capital Services and Morgan Stanley India ran the book. Promoter holding, held by Genius Bidco Holdings and Genius Rajkot Investment Holdings, falls from 100 per cent to 65.58 per cent.
Two things to watch from here. The K-12 acquisition the issue is paying for has to close and then show up in the numbers, and the December quarter results will be the first set Elevate Campuses reports as a listed company. Prices are on our Elevate Campuses IPO page, and you can compare this open with every other mainboard debut on our mainboard IPO listing performance table.
Frequently asked questions
What was the Elevate Campuses IPO listing price?
₹355.10 on the NSE and ₹356.50 on the BSE on 30 September 2026, against an issue price of ₹362.
How many times was the Elevate Campuses IPO subscribed?
1.79 times overall, with QIB at 2.52 times, retail at 1.01 times and NII at 0.84 times.
What was the Elevate Campuses IPO lot size?
41 shares, which cost ₹14,842 at the upper band of ₹362.